Guides United States

United States · Financing · 4 min read

Most of the capital is borrowed. The lender still needs the site to work.

A US franchise unit is usually financed, and often through a lender using a Small Business Administration guarantee. The structures are well published. What they share is an assumption no loan document states: that the unit will trade well enough, at that address, to service the debt.

Published · Published industry and statutory figures, restated with sources. Not legal, financial or investment advice.

  • SBA 7(a) loan
  • SBA 504 loan
  • SBA Franchise Directory
  • Franchise financing
  • Debt service coverage ratio

SBA programmes

7(a) for the business, 504 for the building.

Under the SBA 7(a) programme a qualifying franchisee can borrow up to $5 million for leasehold improvements, equipment, opening inventory, working capital and the initial franchise fee. The SBA guarantees 85% of a loan of $150,000 or less and 75% of a larger one to the lender. Published lender terms run up to 10 years for working capital and equipment and up to 25 years where real estate is financed, and a personal guarantee is standard.

The 504 programme, with a maximum of $5.5 million, is built for fixed assets: land, ground-up construction and long-life equipment. It pairs a conventional first lien of about 50% of the project with a Certified Development Company debenture of about 40%, backed by the SBA, leaving the borrower to put in 10% to 20% as equity, on fixed-rate terms of 10, 20 or 25 years.

Scroll sideways to see all columns

Published programme and industry figures, restated. SBA limits, guarantee percentages and eligibility rules change; confirm current terms with an SBA lender before relying on any figure here.
VehicleLimit and structureTermsTypically funds
SBA 7(a)Up to $5 million; 85% guaranteed up to $150,000, 75% aboveUp to 10 years (equipment, working capital), 25 (real estate); personal guaranteeFranchise fee, tenant improvements, fixtures, opening inventory, working capital
SBA 504Up to $5.5 million; ~50% bank lien, ~40% CDC debenture, 10%–20% equityFixed rate over 10, 20 or 25 years; secured on the assetLand, ground-up construction, long-life equipment
Equipment financeSet by the lessor or manufacturer3 to 7 years; secured on the equipmentPOS systems, kitchen lines, fitness equipment, vehicles
Tenant improvement allowanceLandlord credit, commonly $20 to $100+ per sq ftPaid against construction draws, usually at certificate of occupancyHVAC, plumbing, partitions, electrical

Eligibility

The brand has to qualify before you do.

An SBA loan to a franchisee depends on the brand. The SBA dropped its central Franchise Directory in 2023 and reinstated it in its updated lending procedures, SOP 50 10 8, effective 1 June 2025. A brand needs an active SBA Franchise Identifier Code and franchisor certifications that its agreements do not breach the SBA's affiliation rules — the test of whether a franchisor controls a franchisee so tightly that the borrower is not an independent small business.

Ask the franchisor for its SBA Franchise Identifier Code early. The lender will check it, and a brand missing from the Directory can stall an otherwise approvable loan after you have already committed to a site.

Underwriting

1.25 times the debt, from one address.

Lenders test whether a unit can carry its loan with the debt-service coverage ratio: cash flow available for debt service divided by annual principal and interest. SBA and conventional lenders typically look for at least 1.25x to 1.35x, and it is the covenant the loan is then held to.

Every input to that ratio is local. Sales depend on the trading area, occupancy cost on the lease, labour on the local wage. A franchise system's record helps a candidate get through the door; it does not transfer to a weak site, and the personal guarantee means the shortfall is yours.

  • SBA 7(a): up to $5 million, 75% to 85% guaranteed to the lender
  • SBA 504: up to $5.5 million; ~50% bank, ~40% CDC, 10% to 20% equity
  • Tenant improvement allowance: commonly $20 to $100+ per square foot
  • Debt-service coverage: 1.25x to 1.35x as a typical minimum
Where this platform fits

Test the site against the debt before the lender does.

If you already hold or are being offered a property, the lender's question is whether it can carry the loan. FitFinder reads one locked site and tests which categories and franchise formats its demand, competition and physical fabric support — and what a target return would require you to change.

  • Categories assessed first, brands second, against one fixed address
  • Rent, deposit, floor area, staffing, royalties and capex all adjustable inputs
  • Conservative, base and upside scenarios with your budget visible throughout
  • The gap stated plainly when nothing clears the return you need

Modelled scenarios are planning tools on stated assumptions, not the cash-flow projection a lender underwrites. Build that with your accountant on the franchisor's disclosed figures and your actual lease terms.

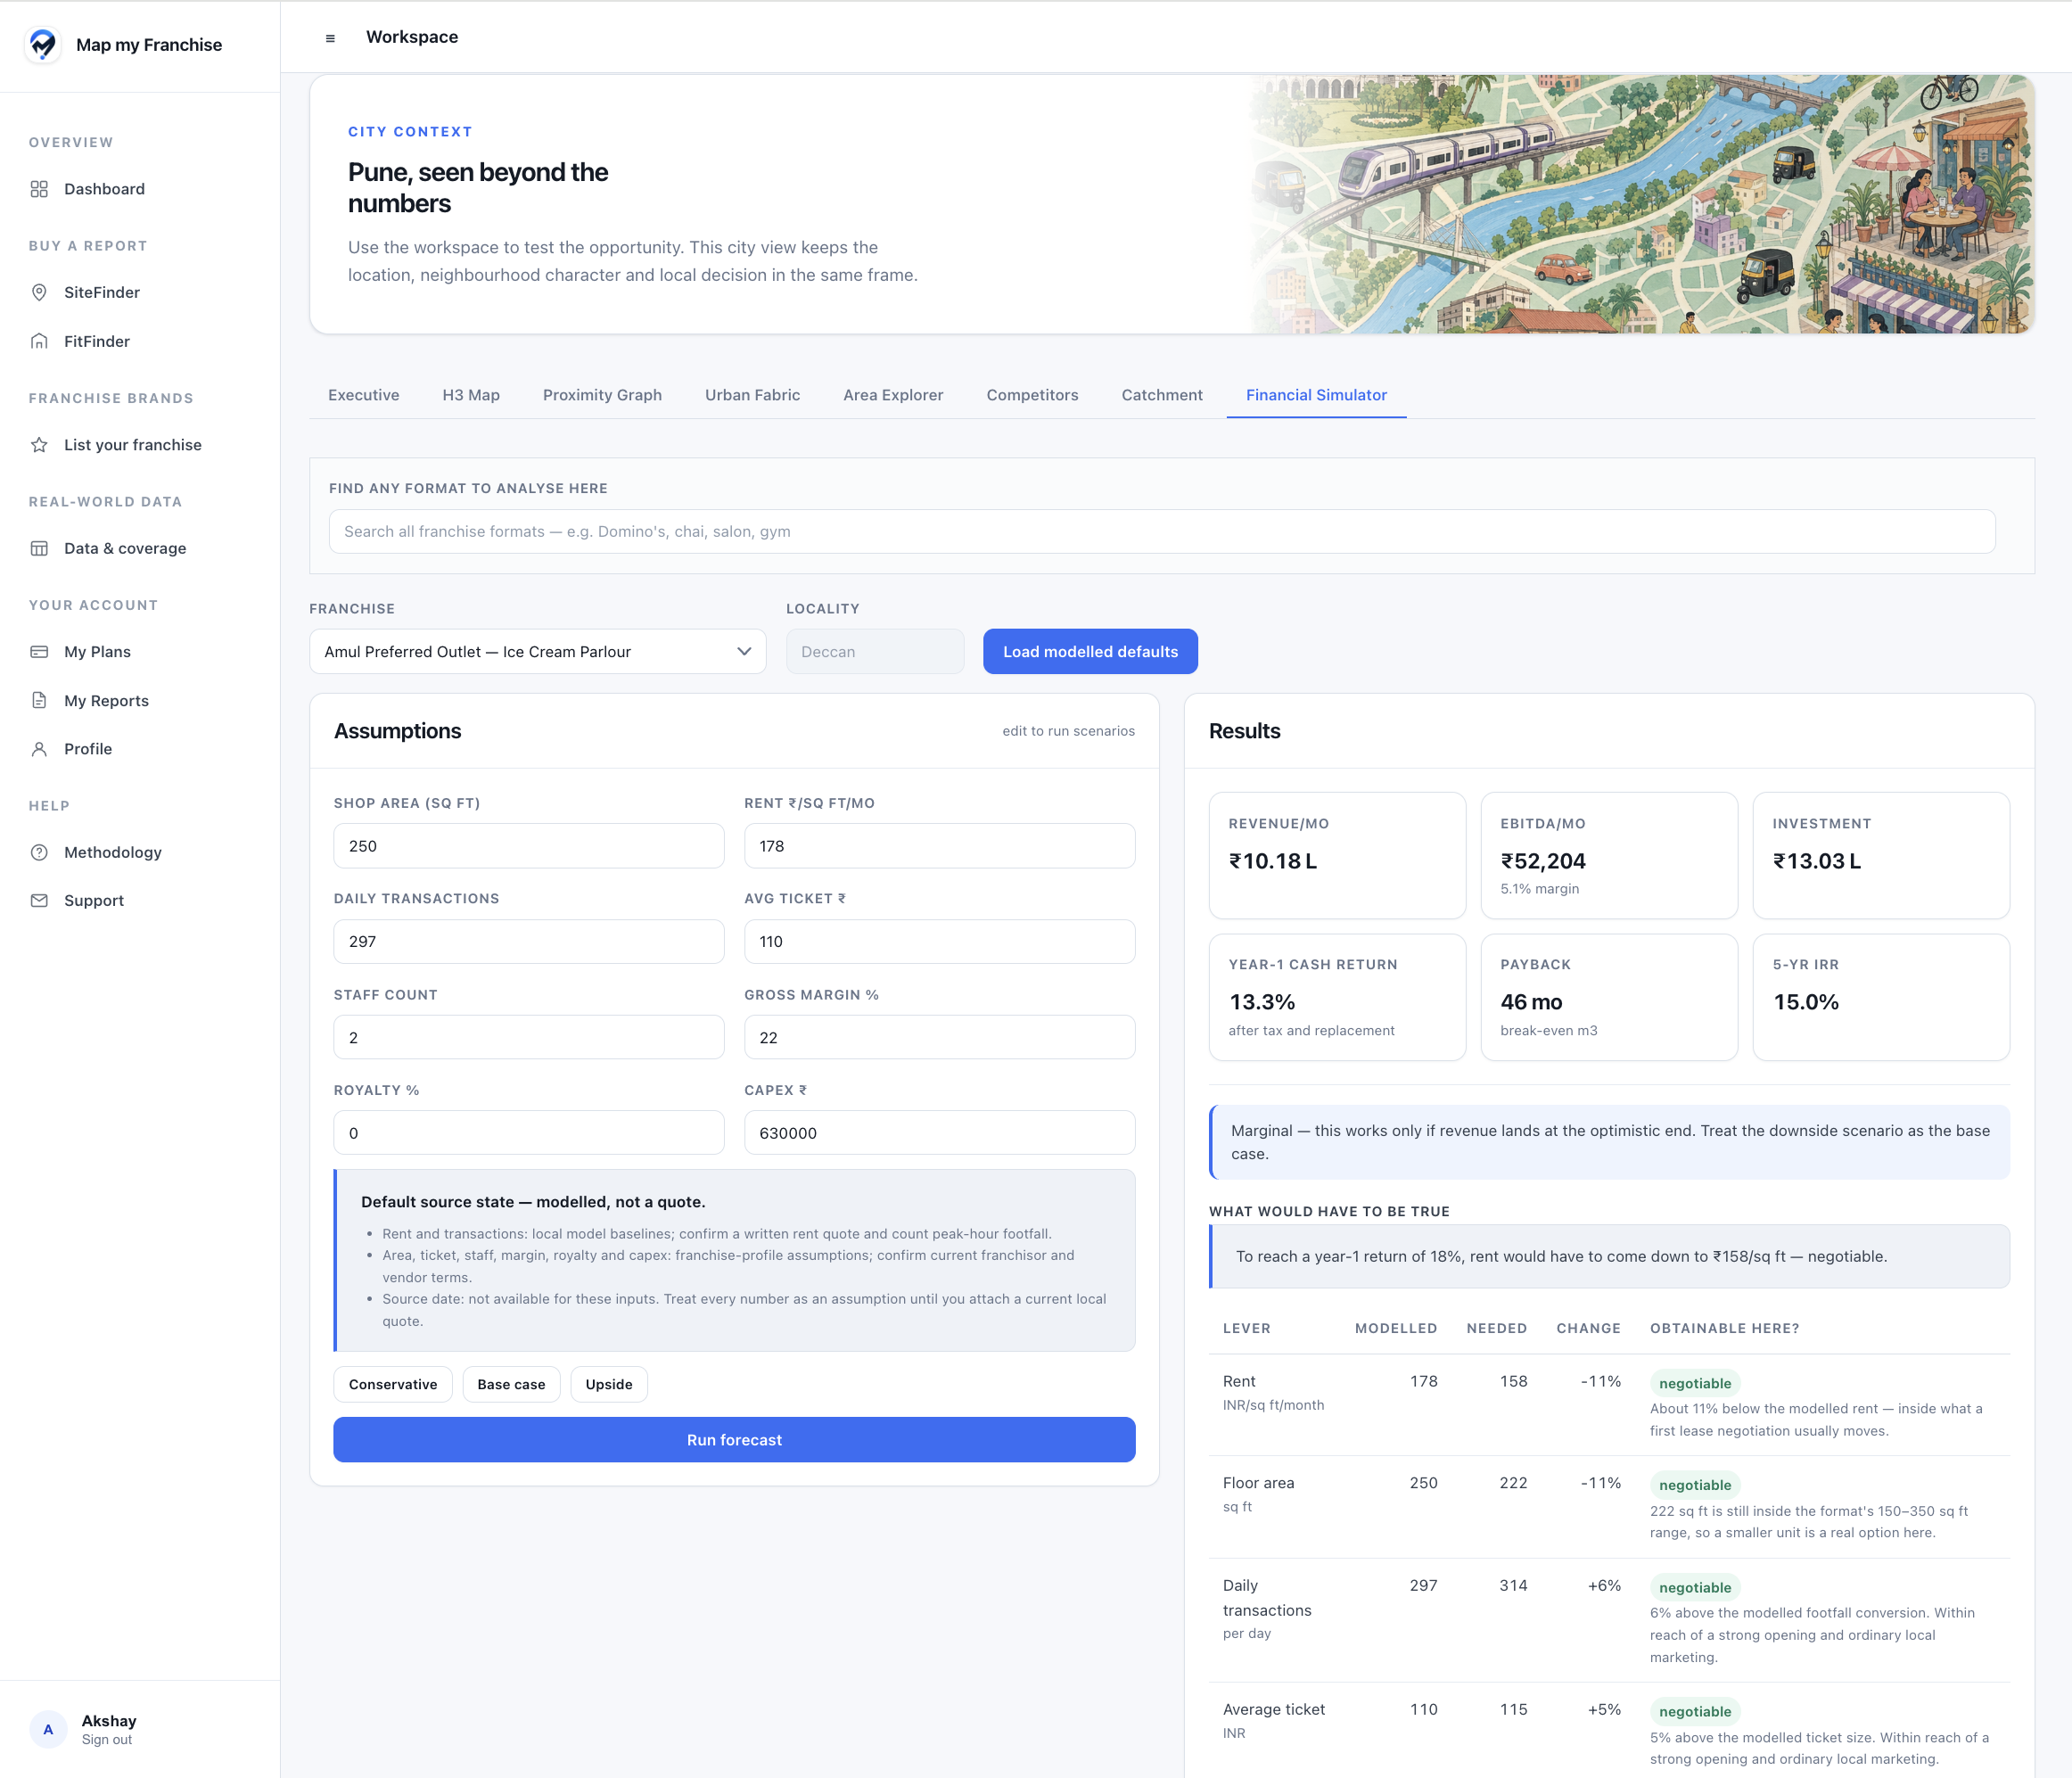
Product example · Pune, India. Modelled planning scenarios.

FitFinder Financial fitActual product screen
FitFinder financial simulator showing Amul assumptions, modelled returns and a table of rent, area and transaction changes needed to reach a target. Original product screenshot Enlarge & inspect
Amul Preferred Outlet · Deccan. The target-return calculation is a scenario, not a guarantee that the required rent or trading levels are achievable.
Where FitFinder is available today
  • Open for purchase now: any city in the world. The report is delivered within 2 days of payment. Featured cities: Mumbai, New York City, Pune, Dubai, Nagpur, Gurugram, Rajkot, Copenhagen.
  • Open in United States: every town and city — featured cities include New York City.
  • BrandReach carries no city, so a brand anywhere can be listed today.
Ask about a US city

Questions this guide raises.

Can an SBA loan pay the initial franchise fee?

Published lender guidance lists the initial franchise fee among eligible 7(a) uses, alongside leasehold improvements, equipment, inventory and working capital. Whether your loan covers it turns on the lender, the brand's Directory status and your own credit and equity, so confirm it with an SBA lender before committing.

What debt-service coverage ratio do SBA lenders look for?

Typically at least 1.25x to 1.35x: the unit's cash flow available for debt service should exceed its annual loan payments by a quarter to a third. It is a lender's floor, not a target — a unit trading at exactly 1.25x has little room for a slow season or a rent review.

Sources

This guide restates published material. Where a figure matters to a decision you are about to make, read it at the source — regimes change, and a summary is only as current as the day it was written.

Statutory disclosure windows, lease regimes and competition rules differ by jurisdiction and change with legislation. Nothing on this page is legal, tax, financial or investment advice; take the documents in front of you to your own counsel.

Bring the evidence
into the decision.

See plans & pricing

Product screenshot

Read details opens at the key analysis. Scroll to explore; Actual size shows every pixel.

Original product screenshot. Example values and assumptions require verification.